Your super-simple totally guaranteed 12-step plan to mobile app success in China (or complete failure)

The list of Western apps that have made it big in China is not long. There are some great games on that list, including ones from major studios Supercell and Riot Games. Games like Cut the Rope and Fruit Ninja made the cut, and Subway Surfers and PUBG are big globally as well as in China.

But as Josh Burns explains, it’s probably easier to list the apps that failed.

He has a lot of experience with apps in general and China in particular. 

As a former exec at 6waves and EA and founder of DigitalDevConnect, Burns has helped launch games for Kabam, Nexon, and Atari. He’s managed games with IP from Disney, Starz, Eminem, and the BBC. Now, among a few other things, Burns helps top grossing mobile games enter the China market.

I chatted with him recently, and along with a lot of advice about what NOT to do, he shared 12 keys to success in bringing mobile apps to China. 

Here’s his best insight about taking apps and games from the west and bringing them east. (Note: quotes are edited for clarity and length.) You can also listen to my chat with Josh on the Growth Masterminds podcast.

————————————————————————————————————————————

This is part 3 of a series on mobile in China:

————————————————————————————————————————————

12 steps to China: keys to entering the Chinese mobile ecosystem


1 . Innovate, but not too far

China might be a different world, but it’s not entirely different. And some of the advice about what works in China is, frankly, good advice about growing your app anywhere.

Innovate, but don’t come to the market with something totally incomprehensible.

“Incrementally innovate in a way that there’s something that’s familiar, but enough that’s unique and different,” Burns says.

Of course, that’s much easier said than done. But so are most things in business, and in growing apps in China.

2. Do your due diligence

As you look to enter the Chinese mobile ecosystem with something that’s innovative but not crazy out-of-this-world and open yourself up to the possibility of lightning striking, it still pays to get some market intelligence.

“Obviously do you want to do a lot of due diligence in advance,” Burns says. “Is there something out there that has any sort of traction?”

In other words: skeletons in games in China? There’s probably a reason why. No first-person-shooter featuring a zombie apocalypse? That might be a clue about what not to do.

3. Go incremental … be agile not waterfall

A huge number of companies are agile in development but waterfall in strategy, especially when it comes to China. So they do too much before they know if any of it will pay off.

“What I see a lot is companies invest crazy amounts of effort into this extensive plan: Okay, we’re going to first want to translate the app. And then we’re going to look to localize the app store pages so that it resonates better with the local audience in terms of the graphics. Then I’m going to look at maybe adding some additional features. Maybe it’s a consumer app that has content … video content or photo content, or even animations to make it more relevant. Then I’m going to look at these local channels for marketing or acquisition,” Burns says.

“You know, they do all of this work in advance,” he adds. “And the reality is you make the app live on the app store with a translation and you realize in a couple of weeks that nobody cares.”

The lesson is clear: start small, start cheap, start easy. If you see signs of traction, continue to invest.

Practically, that means: start with a translation. Get it in the app stores. See what happens. React based on the data.

4. Test your unit economics before spending big

Again, good advice about breaking into the Chinese mobile app ecosystem is probably good advice for just about any game or app launch. Test your unit economics before spending the big bucks, but then also add another layer of due diligence. 

Take a hard look at the profitability of your entire China venture, not just the in-China user acquisition and LTV results. What’s left after all your costs are covered?

“You can do a lot and make a lot more money, but is it actually profitable?” Burns asks, mentioning a mobile brand that went to China and had what looked like success. “The guy was like, yeah, we made a ton more money. But in the end, when you look at the revenue share and the effort and the resources, we have maybe like 5% profit or something.”

Going to China is great. Success in mobile in China is great. But resources invested in mobile growth in China cannot be invested elsewhere. So you have to think hard: where else would you spend that cash? Could it be more profitably invested elsewhere? Is China the best place for your executives to be spending time and focus?

If so: great. Knock yourself out.

If not, a penny saved is a penny earned. Make your shareholders happy.

5. Save your pennies

Talking about pennies, save them up. You’re going to need a lot of them.

“The investment to enter the Chinese market is not insignificant,” Burns says.

But you knew that already, right?

6. Partner up

Sometimes business strategy and business necessity collide. As we mentioned in the first blog post in this mobile-in-China series, you simply need a local partner with local ownership to get up and running. It’s a legal requirement in most cases.

But you also need a local partner to be successful from a growth point of view. Local market understanding, insight, and reach is critical.

“A lot of it (success) is aligning yourself with a local partner to assist you in the market,” says Burns. “Some of the biggest games that are most successful … they all had a local partner to help with operating the game in the Chinese market.”

7. Lawyer Up

As we shared in the second blog post in this series, you need no fewer than seven different business licenses and legal filings to launch in China. That can take a while, and it involves a lot of complexity, especially if you offer in-app purchases.

“There’s a lot of regulatory complexity,” Burns says. “There’s a lot of ways you can get yourself in trouble.”

Get the right help that knows how to navigate through Chinese regulations and bureaucracy. Rely on it. Realize that you won’t cross every T and dot every I in a week or two.

8. Engage users in different ways: use the Chinese social channels

Unsurprisingly, China is not America or Europe. People are different, and they act in different ways. When they have a problem with a game or app, they expect support. And they expect it to be speedy and available on the channels that they use.

“Be intelligent about how you engage your users … be able to do customer service over WeChat,” says Burns. “People who spend a lot expect very high touch customer support.”

That might be unheard of in the west: customer support for a mobile game that doesn’t involve email or some web form that probably will never get answered. But it’s a basic requirement, certainly for high-value users or customers, in China.

9. Know local taboos

It’s not just customer support. Regulations and what’s socially acceptable are different in different countries, and in China, that means no zombies. And no skeletons, among other things.

“There’s things that you wouldn’t necessarily think about, like skeletons in your game is a taboo thing,” Burns says, adding that some games have had to tone down the violence. “PUBG tried to release the original version, but they changed it to be less gory.”

Your local partners — you have them, right — can guide you through those cultural and legal minefields.

10. Follow initial success with more incremental steps

So you were smart. You launched with a minimum viable China product: you translated it and you launched it on the various app stores. Now you’re seeing traction. 

Nope. It’s not yet time to blow the bank.

Keep with the agile, incremental, low-spend approach.

“You have a product that works … how can you modify it slightly to be more relevant?” Burns says. “If you have social sharing, can you support the local channels like WeChat? If you have a microtransaction or some type of in-app purchase model … Chinese users are used to making very very small payments, small purchases, so you may want to look at your business model set-up from that perspective.”

Once you’ve made those changes, check for results. Do they move the needle? Did they pay for themselves, and then some? Do they indicate that doing more might make sense?

But be cautious:

“If you have to reinvent the wheel, it’s not going to be worth it,” Burns suggests.

11. Pray for dumb luck

Look, we all know that hope is not a strategy, right? And yet, dumb luck plays a huge role in what works and what does in mobile, including in China.

Success seems inevitable after the fact, but it’s anything but. And even big winners elsewhere get no guarantees.

“If you had shown Clash of Clans or an early Supercell game to somebody in the Chinese market, they would tell you ‘Oh, you know, this won’t work. People don’t enjoy these types of simulation-based building games’ … but it obviously did,” says Burns.

Some say they’d rather be lucky than good. Best strategy: work at both.

12. Remember, success is an outlier

So much of what works in games and apps is seemingly chaotic. Who would have thought that a crazy-simple hypercasual game like Flappy Bird would capture the world? Who could have predicted that Pokemon Go would not only be a huge hit but would continue to be a massive and strong game franchise for half a decade now?

So remember that success is an outlier, and try something different.

“People are looking from the lens of what’s already worked or working. And so anything outside of that, they say, well, that’s not going to necessarily work here,” Burns says. “A lot of the foreign successes in gaming were because they were innovative and different and not something you could have predicted.”

That’s true in general in almost every vertical … and it means you can’t predict whether your product will resonate and succeed. That is why, as they say in sports, you play the game. Sometimes the champion wins; sometimes he or she loses. And sometimes the underdog becomes the new champion.


In some cases, this is all nonsense

Incrementalism is great, but for some mobile publishers at massive scale who partner with a Tencent or a NetEase … that’s not going to cut it.

If a massive Chinese mobile publisher agrees to partner with you, they’re going to expect massive investment and cooperation in working together to build your app or game into a huge success in China. A few million downloads doesn’t move the needle for players of this size, so you’ll be swinging for the fences.

For smaller players or those who don’t have such enormous partners: go the smart path. Start slow and build as you see progress.


Going to China? Singular can help

Singular is a global MMP with services in China as well as the rest of the world. Book some time with one of our experts to chat about how Singular can help you grow your business in China with our China-specific attribution services that include deep integrations with all of the major industry players.


14 ways mobile games user acquisition is changing in the era of SKAdNetwork

One of the key drivers of economic growth in high-tech economies over the past decade has been performance marketing on mobile. In no vertical has that been so obvious as mobile games, an ecosystem with over 3 billion customers we call users and revenues approaching $100 billion/year. 

But mobile user acquisition for games is entering a new age, and much of what we know and how gaming studios and publishers act will have to change.

We are entering the era of privacy: scarce IDFAs, aggregated data, limited targeting.

The critical question for anyone who makes a living making, managing, or marketing mobile games now has to be: what’s changing with mobile user acquisition in 2021 and beyond? What remains from the best practices of the past decade? 

And what will I have to learn — or unlearn — to be successful?

Let’s start here: mobile games user acquisition in the past

Mobile marketers had old-school user acquisition down pat.

Here’s the recipe:

Build a great game. Soft launch it in New Zealand. Test and iterate and improve. Launch it in the US and major global markets. Add some app store optimization. Sprinkle in some social promotion. Kick-off some cross-promotion with your other apps, and maybe with apps from other studios or publishers. Get a good feel for LTV. As you start to think you know what’s what, kick-off paid user acquisition via mobile ads in scale. Buy banners and rewarded videos and playables and other placements. Spend widely. Test multiple channels. Hit the charts if you can by coordinating spend to amp organic. A/B and multivariate test your ads and creative. Measure the costs of installs and users. Ensure it’s below LTV. Double down on effective channels. Eliminate partners that don’t perform. Build engagement and loyalty. Add social, and incentivize users to share and bring in friends.

Rinse.

Repeat.

Rinse.

Repeat.

If you’ve done it right and your game doesn’t suck and the magic pixie dust of the internet smiles upon you, laugh all the way to the bank as hundreds of millions of users drive billions of dollars of value and Wired writes a fawning story about “the new wave of mobile.” 

Buy a copy to mail to your mom.

Sell to Zynga or someone else with deep pockets and an appetite for growth. Keep following the playbook, or cash in your chips and buy the $4 million 800-square-foot condo in San Francisco.

Mobile user acquisition for games in the future

Everything changes in the age of privacy. Targeting is hard. Retargeting is impossible. Measurement has new wrinkles. Gamer valuation is more difficult. 

What do you do?

Some old standbys are still relevant.

ASO still matters, and is arguably even more important now. App Store Optimization should not just tell the right people why they need to get and play your game, it should also tell the wrong people who will just cost you marketing money and churn to not get your game. Soft launching is still valuable, social can still help a bit, even if the likelihood of going viral like a Pokémon Go is somewhere between astronomical and metaphysical.

And actually building a great game experience will never go out of style.

But here’s 14 things that are changing user acquisition in iOS 14.5 and SKAdNetwork.

14 updates to mobile user acquisition strategy in 2021

  1.  Team up: apes together strong
    “Apes together strong?” Probably stronger than seperate. While one app alone has limited insight into users and the device identifiers that remain, multiple apps from the same publisher can share IDFVs and engage in cross-promotion. It’s unclear yet if this strategy will be super-effective, but it’s one we’re already seeing in the market, and it’s worth considering along with all your other options.
  2.  Advertising intelligence: no more spray and pray
    Hypercasual games in particular have tended to adopt high risk and high reward ad campaigns: spraying ads wherever possible, especially to audiences of known payers, in the hopes of landing a whale. In iOS 14 without IDFAs, you’ve got less intelligence and spraying and praying potentially goes from high risk, high reward to just plain old high risk. Ad spend might suffer as a result: performance marketers don’t keep spending without reward.
  3.  Creative resurgence: time to get funky
    Targeting is worse, tracking is gone, and the big network black boxes still exist. Creative is your differentiator. It’s now time to unleash your creative and try seriously out of the box ideas — AKA weird sh!t — and get attention. You will pay a price for misleading creative in a mobile ad, but you will win when you hit a home run with creative that tells a true story and drives 10X attention and action over mediocre ads.
  4.  Advertising changes: lower costs, lower returns
    iOS ad prices jumped pre-iOS 14.5. But going forward with targetability down, some publishers with non-premium and non-homogenous audiences will find that their ad revenue isn’t as high. Great publishers with highly verticalized users might be insulated from this change because they allow mobile games publishers to precisely hit a pretty clear target audience, but that’s likely an exception. Advertisers should find more pockets of affordability among most publishers. The only problem: the traffic is worth exactly what you paid for it. Cost per install might be down, but the percentage of quality users is likely to trail off too.
  5.  Conversion values: playing high-stakes poker
    Getting SKAdNetwork conversion values right is going to be where mobile marketers earn their keep. Getting just the right amount of data to enable future advertising optimization decisions in as close to real-time as possible will be incredibly difficult. It will also require working closely with the product team to optimize onboarding and early engagement flows. (It’s almost like you need some way of modeling SKAdNetwork conversion data so you can test the impact of changes without actually making them.)
  6.  Data science: you thought you needed it before?
    If you thought you needed data science before, think again. In the past you had IDFA data on iOS (most people didn’t turn Limit Ad Tracking on) and you had GAID data on Android … and attribution and measurement were relatively simple. You still have IDFA for iOS 14.5 — some people will opt in — but now you need to account for SKAdNetwork data as well. Plus any other incrementality or media mix modeling you might be doing. And any magic that might be going on to understand and optimize your conversion values. In other words, you need even more data smarts now.
  7.  Onboarding gets critical: maximize D1
    In the world of IDFA, post-install engagement and conversion data is the gift that keeps giving for as long as a user stays active. In an SKAdNetwork world, user acquisition relies on a limited set of data for a very limited amount of time. That means you need to onboard new users efficiently and effectively … and basically immediately. If you don’t do that you don’t know enough about them to understand the value of your cohorts, and you don’t have great information to optimize future marketing campaigns.
  8.  Post-acquisition marketing: WoM and viral go boom
    Virality is always a good thing. It was a good thing before iOS 14.5 and it’ll be a good thing in the era of privacy, because “free” users in mobile games are like found money. But when paid marketing has some new roadblocks and intentional haziness, anything you can add via social, viral, word of mouth, and other existing-user-driven organic means becomes even more important. And, naturally, drives cost per install way, way down.
  9.  Channel & partner shake-up: last-click apocalypse
    Some channels and ad partners have gotten incredibly good at optimizing for last click. Or at taking credit for mobile ad views which just happen to have been The Critical View™ in a mobile gamer’s app install odyssey. Well, though IDFA was largely last-click in practice and SKAdNetwork is largely last-click in construction, there’s an increased awareness of incrementality as a valid measure of marketing in a data-diluted ad ecosystem. And, of course, with SKAdNetwork’s recent “loser postbacks” and view-through attribution support, there’s more momentum than perhaps any time in the last decade for a more nuanced view on mobile attribution and marketing measurement. That has implications for ad networks and mobile platforms that have focused on winning the last-click sweepstakes, and will result in changes in which channels mobile advertisers use going forward.
  10.  Cross-platform user acquisition: expanding “mobile” marketing
    Even if you want mobile users because mobile is now the operating system of life, the economy, and because — of course — it’s also the primary way people play games today, mobile marketers can continue to expand the scope of their non-mobile marketing. We’ve seen it in the past: TV ads for DraftKings or other mobile properties, with relatively crude measurement looking for bumps in “organic” App Store activity and user acquisition. And we’re going to see more of it because as non-deterministic or at least non-granular modes of attribution gain traction, you’re going to be able to measure TV or out of home or other traditionally “brand” focused campaigns alongside your “performance” campaigns.
  11.  Consolidation is the new platform: move over, SANs
    There’s a reason Digital Turbine bought Fyber and AdColony. And Applovin bought Adjust, and Zynga bought Chartboost. As third-party data gets scarce and unreliable, industry players are building bigger castles of first-party data. When you can’t share across silos, you build bigger silos with more inside. That means increasing the ability for a mobile app developer or publisher to advertise, monetize, measure, drive engagement and maybe even more all inside one massive privacy moat. Individual players are teaming up, and that means a proliferation of what we can call platforms. Of course, it also means more silos of data for the mobile marketer to assemble for a complete picture of action and reaction, or spending and ROI.
  12.  Brand and performance kiss and make up … and discover they’re related
    Brand and performance advertising have never really been totally separate, in spite of the way we’ve often treated them. But our measurement methodologies have prioritized “measurable” channels (surprise, surprise). And — also no surprise — our measurement methodologies have been focused on things that have been measurable. With more MMM and incrementality, we’ll see more clearly how traditionally “brand” advertising has a performance component, and how traditionally performance marketing has a brand component.
  13.  Monetization changes: more subscriptions
    Subscriptions have been hot for a while. But that’s only going to increase as the user acquisition game changes. The ecosystem is moving towards more of a lifecycle marketing approach targeting not just higher value new users but also longer term users. This is a step away from the ad-driven endless wheel of gaming user-recycling that we used to see, and more towards longer-term relationships in quality games with quality users. Or, should we say, customers.
  14.  Retention for the win: you don’t have to get what you don’t lose
    When marketing gets more expensive or marketing gets more difficult, it’s a good idea to look to customer retention or user retention strategies. Keep what you have, plug the leaky bucket, and you don’t have to top it up with as much water. That saves money and effort, long term.

Everything changes, especially in mobile growth

User acquisition strategy has never been a static thing. It’s always been changing rapidly as smart mobile marketers discovered new tactics, technologies, and means of driving app installs and reducing costs.

The iOS 14 change is just a very big and very sudden one, and it’s likely to be accompanied by another adjustment on the Android side in 12 to 24 months. The good news is that marketers in mobile gaming tend to be very flexible and quick to learn.

Every change is also an opportunity for those who are willing to embrace it and learn faster than the competition. User acquisition winners in the new paradigm are going to be people like that.

Singular can help

Singular was the first MMP to support SKAdNetwork. We also have access to more data than anyone else, thanks to integrations with thousands of ad networks and platforms for campaign, bid, spend, and creative data. We combine that with world-class marketing attribution data for a complete picture of your marketing inputs and outputs.

Book some time with us today to chat about how we can help you accelerate growth, even during uncertain and changing times.

8 limitations of SKAdNetwork for mobile marketing measurement

SKAdNetwork may be the only game in town for mobile marketing measurement and attribution on iOS 14.5 and following for the foreseeable future. And it offers some significant benefits: deterministic attribution of app installs on the iOS App Store. But there are also some major SKAdNetwork limitations.

The IDFA, after all, offered attribution data that was deterministic too. 

But it also provided device-level granularity. Deep linking functionality with deep linking measurement and tracking. Extensive post-install app events for conversion reporting and ad campaign optimization. Data on ad impressions. Data on ad clicks. And, of course, an identifier for retargeting and look-alike audiences.

That’s in the past.

But there’s still some value in understanding as much as possible about SKAdNetwork limitations so that mobile marketers can optimize around them. I spent a few minutes with Singular CTO Eran Friedman to understand those SKAdNetwork limitations and get some insight into how to maximize the data that SKADNetwork does supply.

8 SKAdNetwork limitations

1. Distributed postback data

Mobile measurement partners invented the concept of the postback for mobile attribution about a decade ago. It’s simply a digital notification of an event. MMPs collected them for all the different ad networks and media partners a marketer used, and marketers automatically had a centralized repository of app installs, attribution data, ad network contributions to their marketing success, and more.

Under SKAdNetwork, when someone sees an ad for an app, clicks on it, and installs the app, a postback is sent from their mobile device directly to an ad network. If you, like most mobile advertisers at scale, use 10 or 20 or even more ad networks, your mobile app marketing attribution data is now scattered across all those companies’ servers.

(Note: Singular has fixed that problem with our SKAN solution.)

2. Limited granularity

The old way of doing mobile attribution on iOS gave perfect granularity. As long as someone didn’t set Limit Ad Tracking on, their IDFA was fully available to advertisers, publishers, and all the various layers of the adtech stack. That gave you device-level data on ad views, clicks, installs, and post-install activity and conversions.

That’s still possible, but it requires app-by-app permission for everything to work as it used too. Getting IDFA permission is great, but if it’s only on one side of the advertiser-publisher relationship, it’s insufficient. You’ll need permission on both the publisher app and the advertiser app to make it really work.

In SKAdNetwork, granularity is limited:

  • No device-level data
  • No creative-level data
  • Only 100 campaigns (and ad networks can use most of their for internal tracking)
  • Publisher data
  • Only 24 hours of post-install conversion data, unless you update the conversion time
  • Only six bits of post-install conversion data

3. No retargeting

In the iOS 13 and earlier era of IDFA, you could retarget former app users or people who have your app installed but aren’t opening it. Using their IDFA, you could target ads with offers to them, incentivizing them to return, reinstall, or reengage. 

Not anymore.

In the iOS 14.5 era of SKAdNetwork and scarce IDFAs, retargeting is essentially toast. SKAdNetwork does have support for a redownload flag so you can know when you’re getting someone back, but you can’t really target them on other apps or via ad networks like you used to be able to.

4. No look-alike campaigns (or … look-alikes with reduced effectiveness)

IDFA made look-alike campaigns possible. Using your attribution data, app events, and conversion values, you could build lists of your best users or your top customers. You could then export this list of IDFAs and send them to your ad partners, telling them to find more users like these.

Because ad networks and major platforms like Facebook, Google, Twitter, Pinterest, Snap, and TikTok have a lot of data about ads that devices with those IDFAs have clicked on and apps that they’ve installed (plus more data in many cases) they could find you more people like the best users and customers you already had.

Guess what: no IDFA, no look-alike campaigns.

“Things like lookalike campaigns, for example, rely completely on the IDFA,” says Friedman. “So they’re just completely unsupported by SKAdNetwork.”

Now, platforms are doubtless exploring ways they can offer look-alike-like products to advertisers, but the reality is that without IDFA, there’s going to be some new level of uncertainty, probability, and modeling in the audiences that they assemble. So there’s an inevitable loss of granularity and deterministic targetability, which will degrade effectiveness to some degree.

5. No real multi-touch attribution

The good news about SKAdNetwork limitations is that Apple continues to iterate the framework. And in iOS 14.6 we got a little gift: loser postbacks.

(OK, that’s my private name for them.)

Most postbacks are “winner” postbacks: a notification that your ad network’s ad impression was successful. It generated a click and the click resulted in an app install. With iOS 14.6 and SKAdNetwork 3.0, however, we got a little gift from Apple: postbacks to up to five other ad networks whose ads were seen but not clicked on, or, at least were not responsible for the app install.

In other words: loser postbacks.

That’s good, but it’s not really sufficient for MTA. You need more data across more platforms and devices to really enable multi-touch attribution (though it will help in measuring incrementality). Full MTA probably requires data from the web, where we now have app-to-web measurement in SKAdNetwork but don’t yet have good web-to-app data, data from deeplinks, and data from entirely non-Apple and iOS sources.

The reality, of course, is that in the last-click-dominated mobile attribution world of the past decade, we didn’t have MTA anyways. We want it, and maybe even need it — everyone knows that last-click is a horrifically myopic way of looking at marketing measurement — but we still don’t have a real path to it with the current SKAdNetwork limitations.

6. Web to app measurement

With Private Click Measurement, Apple gave us a tool to measure app to web journeys in SKAdNetwork. That’s great, but we also need tools to measure web-to-app journeys.

The unfortunate part: that’s much harder.

You can measure app to web because you have a known environment: an app on iOS with access to the SKAdNetwork framework. On the mobile web, you might be in mobile Safari, in which case Apple could insert some SKAdNetwork-relative code, but you might be in Chrome or Opera or Firefox or some other browser that Apple does not control.

Rock, meet hard place.

7. Fraud, fraud, fraud

The Apple postback for app installs on the iOS App Store is cryptographically signed. Great. But the payload of post-install conversion data about what happens after the install is not. Oops.

First off, post-install conversion data could be faked. (Of course, a fraudster would have to know your conversion schema to make it stick.) But secondly, there’s no country or geolocation data, so you could be getting “high-quality U.S. users” who are actually in Kazakhstan. 

And third, a fraudulent media partner could just replay legitimate SKAdNetwork postbacks repeatedly. Unless you’re regularly checking the details on your postbacks, you simply wouldn’t know.

In fact, Singular is seeing duplicate SKAdNetwork postbacks in the wild right now, Friedman says.(Here’s how Singular is fighting SKAdNetwork fraud, by the way.)

8. Data fragmentation (or siloing)

So imagine you’re all set up. You know exactly what you need to do for SKAdNetwork, and you do it. You’re getting the data you need, and life is good, right?

Well …

“SKAdNetwork data doesn’t live in a vacuum,” Friedman told me. “We’re going to have a mix, basically. You have SKAdNetwork data. You’re still going to have IDFA users … users who have opted in.”

And then there’s campaign data too … the data on the campaigns and spend and creative that you’ve set up with ad networks.

Marketers have to connect all that data to be able to answer questions that need answering: how much am I spending? What am I getting for all my efforts? How many total installs am I getting across all my partners? Adding all of that and tying results to spend is a significant challenge. 

Part of the challenge: deciding what dataset you’re using to optimize campaigns. If it’s largely SKAdNetwork, can you leverage partial IDFA data for insights? And, how are you going to analyze creative … with SKAdNetwork campaign IDs? But if so: do you have enough data

Data silos complicate data analysis. Marketers need tools and guidance to properly tackle them.

Maximizing the value of the SKAdNetwork data you do get

So how do you minimize the SKAdNetwork limitations and maximize the value of the data that you are getting?

It starts with defining your conversion model, Friedman says. Then, ensure that you get clean data in a single place that you can analyze both separately and together with all of your other app attribution data. Analyze it for campaigns and partners that are doing well, and any additional insights you’ve inserted into your conversion models.

Also, however, validate your postbacks for both accuracy and fraud.

That all sounds like a lot of work, and it can be. The easy answer, however, says Friedman is to simply use Singular SKAN.

Need help with SKAdNetwork?

If you’re looking for some quick assistance, we’re ready to talk. Book some time with us to find out what Rovio and many other top mobile brands already know: Singular makes SKAdNetwork easy.

We’d be happy to walk through your plans, your strategies, and how Singular can help.

Mobile app attribution in China: Key challenges, requirements, and steps

You’re a hotshot mobile app publisher. You have tens or even hundreds of millions of users in the U.S., Europe, and South America. You’re growing fast and looking to expand even faster. And you can’t help but turn your wandering eye to that massive and growing country in Asia with 1.4 billion people, 989 million internet users, and literally 40% of the world’s mobile app spend.

Close your mouth. Stop drooling. It’s not going to be easy.

But it is doable, with a bit of knowledge. And some time. And, yes, some investment.

________________________________________________________________________

This is part two of a three-part blog series on taking mobile apps to China.

Check out part one, where we overview the Chinese market. Part three is coming soon.

________________________________________________________________________

If you are looking to get set up to do business in China, you need to be forearmed with some knowledge. As we shared in the first post, almost everything is different: top apps, cloud services, payment providers, authentication vendors, even app UI/UX standards. Oh, and did we mention the language?

(More on how to prepare your app for China in our next blog post.)

There’s a lot of work to do outside of your specific app in order to get set up for business in China. I spent some time with Alon Nafta, Singular’s VP of Product, and Xiaoli He, one of our business leaders in China. The focus of our conversation: what you need to do to launch your mobile app in China, and what you need for mobile attribution once you have it running. That includes needed integrations, fraud prevention, and data processing and storage requirements. And, of course, all the legal requirements run a mobile-based business in China.


Xiaoli He & Alon Nafta


John Koetsier: Let’s start here … how long does it take to get set up to do business in China?

Alon Nafta: All things considered, probably six to twelve months, all things considered. That’s a ballpark: your mileage may vary.

Xiaoli He: Yes it will take some time.You need to get your Business License first,to register your domain,to do ICP Filling to get your ICP License and other related licenses as required.After that you need to set up your local servers and start to operate.


John Koetsier: Where does your technology stack need to live? Your data? And, your attribution vendor’s stack?

Alon Nafta: It’s very simple: you need to have servers in domestic China to process data, and there are limitations around the data that can be sent out. 

In a nutshell, no personal data can leave China.


John Koetsier: What are the most important integrations you need to set up?

Xiaoli He: Tencent, which covers WeChat. Bytedance/Ocean Engine, which also covers TikTok (Douyin in China), Kuaishou, Huawei, Vivo, OPPO, Baidu, and Mintegral is a good starting point.


John Koetsier: What are the data processing and storage regulations in China? Is there legislation similar to GDPR/COPPA that app developers should be aware of when entering the region?

Alon Nafta: There are also a number of cybersecurity regulations in China that companies need to abide by. There’s a good overview of it on Wikipedia.

Xiaoli He: Yes, as the development of internet service and technology, China government is constantly improving laws and regulations to protect user privacy.Game developers need to follow this regulation 关于防止未成年人沉迷网络游戏的通知 (or Notice on Preventing Minors from Indulging in Online Games) which is to protect children under the age of 18 years old. The goal of the regulation is that they do not spend too much time or too much money on games. Players will need to key in their ID number, and by regulation the game can not be played by minors after 10PM and before 8AM the next day . Also, minors cannot play more than 1.5 hours during work days and play more than 3 hours during holiday.


John Koetsier: How can you know that you’re compliant with all the various regulations and laws? Who checks? What’s the process?

Alon Nafta: As a company running web-based services in China you are required to get an ICP license. ICP stands for “Internet Content Provider.” This (and your business registration in China) serve as your official ID in China. In addition, with some of the large partners such as Tencent and Baidu you are getting certified or accepted into their programs individually, somewhat similar to how it’s done with Facebook and Google. 

Xiaoli He: It depends on your business. Take game developer for example. The Local Bureau of Culture, Bureau of Industry and Information Technology and Copyright Administration will issue the licenses and will check whether your operation follows the regulations and laws.

Here’s a list of some of the important components you’ll need when entering the China market with your mobile game:

  1. Business License: 营业执照
  2. Website Internet Content Provider Filing: 网站ICP备案
  3. Network Culture Business License: 网络文化经营许可证
  4. ICP license Alon mentioned: 增值电信业务服务许可证
  5. Also, game developers with in-app purchases will need to get a Game License before they can operate their game. This can be tough, because the number of licenses is very limited: 网络游戏电子出版物审批 (游戏版号)
  6. Game Operation Filing: 文化部游戏运营备案
  7. Software Copyright: 软件著作权


John Koetsier: It looks pretty complicated … what are the consequences of getting it wrong?

Xiaoli He: Your game simply cannot be published and distributed if you do not have the required licenses and certificates.

Alon Nafta: In addition, your app can be rejected and you can be removed from China if you don’t get all the required licenses, or you’re found to be in contravention of the regulations. If that happens, your servers will be seized, your traffic will get blocked, and you will not be allowed to operate.


John Koetsier: what are the unique requirements from an attribution provider to have a robust infrastructure for China?

Xiaoli He: Essentially, you need to set up a local server, integrate with local partners and android stores. Note that Chinese developers like to share revenue (CPS)  with media partners and like to run APK distribution with them as well.


John Koetsier: Is it important to have the same attribution provider in China as you have in the rest of the world?

Alon Nafta: Yes. The most important reason why is to simply have all your marketing data in a single place. Of course, you want to ensure that this single place is the best possible tool for the job (shameless plug: which would be Singular!) Also, you don’t want to have overlaps across users who might travel, or use app stores all over the world via VPN or something like that … but this is not a very big problem.


John Koetsier: What’s different about running mobile attribution in China?

Xiaoli He: The biggest difference is simply that there is no Google Play in China. There are many Android app markets in China: each mobile phone manufacturer has its own app store and there are many third-party app markets online as well. And, of course, as we already mentioned, you need to have a local Chinese business entity and get an ICP (Internet Content Provider) license to run any internet related business.


John Koetsier: How many app stores/markets do you need to integrate with to get 90% coverage?

Xiaoli He: Of course on iOS, you have the App Store in China as well as anywhere else. So you only need one for iPhone and iPad, and that’s a reason a lot of international app developers start on iOS when they try to enter the Chinese market. On Android, there are many as I mentioned, and Huawei, Vivo, Oppo, and Xiaomi are some of the top manufacturers with their own app markets. There’s also 360 Mobile Assistant, Baidu Mobile Assistant, Samsung’s app store, and many more.


John Koetsier: What about mobile app install fraud in China?

Alon Nafta: Just like anywhere else, that definitely exists. You need a mobile attribution provider with a strong fraud suite, and I think Singular’s is best in class here. Clearly, you need to be able to detect fraud on Android especially well, as the majority of the market is Android-based.


John Koetsier: Thank you Alon and Xiaoli for your answers!


Looking to enter the Chinese market with your apps? Book some time to chat about how Singular can help you grow your business in China with our China-specific attribution services and deep integrations with the major industry players.


Rovio SKAdNetwork questions answered: everything you wanted to know about Rovio’s iOS 14 mobile user acquisition infrastructure

If only you could ask one of the largest and most successful mobile publishers on the planet how they are planning to run user acquisition and growth campaigns on iOS 14.5 …

(You can. Sort of.)

In fact, a week ago 1,249 people did on a live webinar where Rovio data scientists, marketers, and executives shared their growth stack set-up, key research findings, strategy, and best tips for others on mobile marketing in a privacy-safe era with iOS 14 and SKAdnetwork. On the call: Rovio’s VP of Marketing Kieran O’Leary, SVP R&D David Mason, and senior data scientist Frederick Ayala, along with Vungle’s senior product manager Rina Matsumoto and Singular CTO Eran Friedman.

The only problem?

1,249 people can’t ask all of their questions in a single one-hour webinar.

So we collected them all, lovingly hounding the Rovians, Rina at Vungle, and Eran at Singular for answers. And, honestly, they were all incredibly generous not just with their time but their expertise. There’s no competitive reason for Rovio to share so much insight with the industry: they are literally doing this for the good of the ecosystem.

So we’ve collected all those questions and answers, and are presenting them here. 


Rovio webinar speakers

Ok. All signed up?

Let’s dive in.

Rovio and Vungle’s SKAdNetwork answers

Q. How is Rovio improving/maintaining targeting under SKAdNetwork?

A. When it comes to SDK-based ad networks, the current targeting capabilities shouldn’t be heavily impacted by SKaDNetwork. In other channels such as Facebook, it’s fair to say that on average we’ll have to go broader and/or leverage interest targeting since this parameter is here to stay – interests are Facebook’s first-party data.

– Kieran O’Leary


Q: How is Vungle adjusting their products to the delay in installs and moving to conversion values?

A. We’re making adjustments in our models to adapt to the new delays in installs. As for the conversion values, we’re working on the conversion value API integrations with MMPs to be able to ingest the data and integrate into our optimizations.

-Rina Matsumoto


Q: What sort of impact do you expect on the efficacy of attribution data via SKAdNetwork as compared to existing methodology of IDFA?

A: It remains to be seen, but if we’re looking at our own take on conversion values, running an analysis on previously acquired cohorts, we can hope for an accuracy of about 90%. If we end up using Facebook’s take on conversion values, this accuracy might be affected.

-Kieran O’Leary


Q: How do you compensate publishers when it’s not clear exactly how Apple decides to send a conversion event?

A: Many networks are modifying their advertiser billing method to a solution where there is no ambiguity in publisher revenue attribution (e.g. CPM). This will certainly impact the economics of ad monetization.

-Rina Matsumoto


Q: What are your thoughts on the SKAN privacy threshold and the potential impact on conversions reporting, and any post-install events?

A: The privacy threshold has a big impact in almost everything, so it is important to monitor it and check that the proposed conversion value schema is not affected by it.

-Frederick Ayala

(One note I’ll add here: Singular CTO Eran Friedman has been doing some significant research on this, and we’ll be sharing that on the Singular blog and in video form shortly.)


Q: How do you think mobile growth marketing departments will change their portfolio budget allocation across channels based on what we currently understand about the limitations imposed by major ad partners?

A: If deterministic targeting disappears, then a variety of new upper funnel channels will look more inviting, such as Influencer Marketing, TV, Podcasts, or even programmatic. On the latter, it was never able to catch up with IDFA-based targeting, but now that the field is more even, there’s a fair chance that performance might get on par with SDK-based channels.

Now, we’re just testing all the new approaches offered by our existing partners, so it’s a little bit early to say that our media mix will be radically affected.

-Kieran O’Leary


Q: Are there any estimates about % of users opting to accept tracking? Do you recommend to ask before the iOS alert to try to have a better acceptance ratio?

A: We have heard about very different opt-in rates, from 10% to 70% in some cases. In regards to the actual flow to ask for opt-in, we are just starting to test it now, and while we’re missing a lot of data points, it seems that to get the best results, the dialogue has to be at the start of the game.

-Kieran O’Leary


Q: Have you done any internal tests on how the consents ratio may look like?

A: Yes these tests are currently ongoing.

-Kieran O’Leary


A: Very early to say as ATT enforcement communication may influence results.

-David Mason


Q: Will Rovio ask ATT permission in its games?  Can you talk a bit the thinking behind?

A: It’s considered and very likely (some tests are currently live) but we need to assess properly the pros and cons of doing it, be it for attribution, ad monetisation, or even targeting in some cases.

-Kieran O’Leary


Q: What percentage of ATT opt in are you seeing?

A: At this point we are the early stage of running tests and we expect the communications around ATT enforcement to influence consumer acceptance so at this point it is difficult to measure.

-David Mason

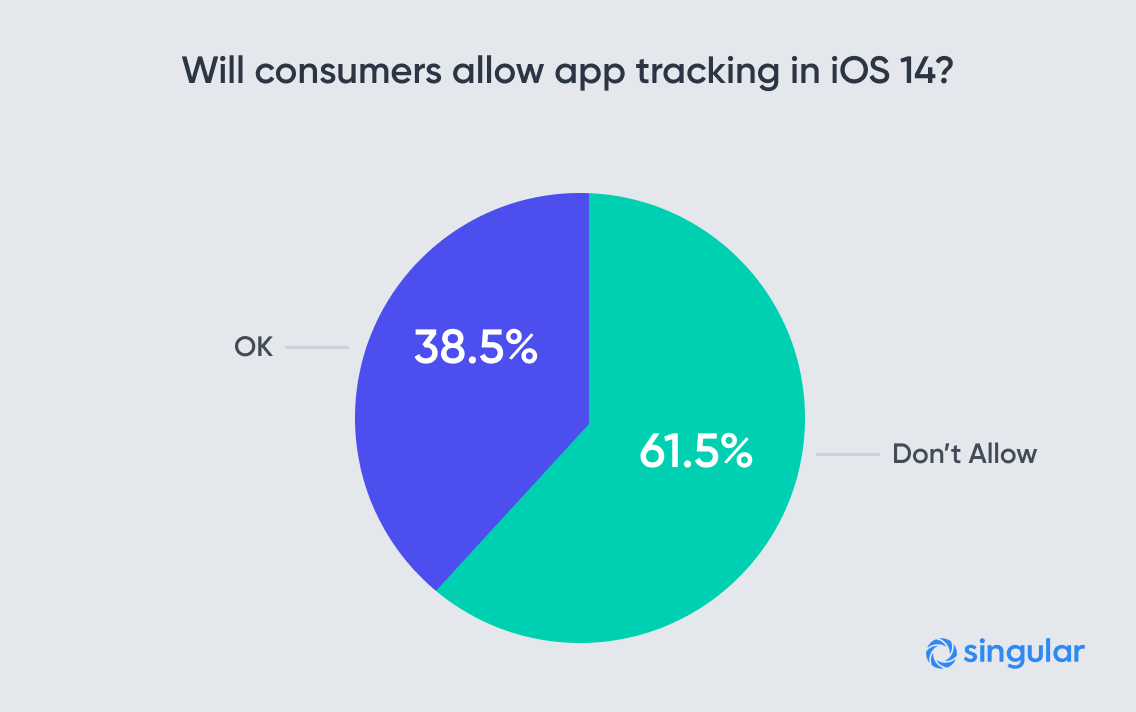
(One thing I’ll add: we found in surveys that 38.5% would allow IDFA tracking. However: real life is different than surveys, and … as this becomes commonplace, that will impact consumer behavior too: think GDPR cookie notifications on websites.) 


Q: Have you increased your Android spends significantly due to iOS 14.5?

A: No we haven’t, and we don’t think it’ll be our strategy. iOS users are here to stay, and we believe we’re prepared enough with SKAN to be able to keep a relatively similar split between platforms.

-Kieran O’Leary


Q: A bit of technical question: How do you deal with the fact that the conversion values can only be updated when the app is open?

A: At this point this is reality and conversion values can only be updated for players active every day.

-David Mason

(If I can read between the lines here: it sucks, and you’re going to lose data, but it is what it is. Your daily active users are likely to be your most engaged and profitable, in any case. Non-gaming verticals like finance and insurance, however, might want to consider engineering their systems for very early data accessibility.)


Q: Do you see a privacy threshold on conversion values? In principle could these be used for user attribution (conversion value – campaign – country combo can be semi-unique)? Do you think that is feasible?

A: There is a privacy threshold and the rules are not communicated by Apple.

-Frederick Ayala

(Personal note: I would caution against trying to engineer a more granular user-level attribution solution out of SKAdNetwork. It will be a lot of work but it will be against the spirit if not the letter of the App Store guidelines … and if you succeed Apple will close the loophole and waste all your effort at some point down the line.)


Q: How does Rovio overcome the challenge to identify user quality early in the funnel (optimizing on conversion events early in the funnel in order to not extensively delay the conversion value information from SKAdNetwork being send back to Rovio/MMP)?

A: We have different conversion value schemas that rely on the first 24 hours. We compare them to check which ones give better revenue estimates and keep the best one.

-Frederick Ayala


Q: A question about Rovio’s paper and conversion value censorship: how do you identify that a certain conversion value was censored? I don’t mean on the postback, but on your user base. The solution presented in the paper seems to assume it would be able to identify which are the conversion values that a censored postback could have. And it is not clear to me: how do you identify it?

A: The paper relies on the total count of null values (those that fall under the privacy threshold) and not in knowing exactly which conversion values were not reported.

-Frederick Ayala


Q: Does the number of distinct conversion values affect the rate at which privacy threshold is applied?

A: From our testing as of now, we don’t believe so. We think it’s more tied to install density in a publisher. With that said, there’s still a lot more to learn about the privacy threshold!

-Rina Matsumoto

(Obligatory shameless plug here: Singular CTO Eran Friedman has been doing some significant research on this, and we’ll be sharing that on the Singular blog and in video form shortly.)


Q: Given we want to optimise on spenders (and not all users), and given that these spenders are a small percentage of the player base, how does the privacy threshold affect the messages from these players?

A: If the conversion value schema places few spenders in certain values then it is likely that all those will fall under the privacy threshold. It is a good idea to backtest the schemas under various assumptions to see how realistic a schema is in terms of privacy threshold.

-Frederick Ayala


Q: What strategies would you follow If you didn’t have all this structure, and are a small dev company using a MMP?

A: Leverage what MMP has built out. We are building on top of Singular and we expect their offering and our own to develop as we all learn.

-David Mason


A: Automate backtesting pipelines and be pragmatic.

-Frederick Ayala


Q: What is your plan for optimization? Because we can not understand which users come from which campaign exactly …

A: With our conversion schema modelling we are expecting to be able to probabilistically attribute players with a high degree of confidence.

-David Mason


Q: Can you please share your calculation for ROI given the limitations?

A: In the short run, we’ll be looking at the larger picture since we won’t be able to distinguish between paid and organic traffic accurately. So our ROAS targets on iOS will have to account for the revenue generated by organic traffic – we’re using historical data about the paid/organic ratio to set them. Then the CV and other methodologies should enable a more accurate reading on our paid ROAS.

-Kieran O’Leary


A: You can check the details of the method in our paper on revenue attribution. At a glance, the method has two steps. First, we calculate the actual average revenue per conversion value and multiply it by the count of each conversion value. Then, we distribute the revenue that could not be attributed from known conversion values (because of privacy threshold) based on the distribution of null values.

-Frederick Ayala


Q: What is the main KPI of creative performance (CTR, IPM, Spend, ROAS) at Rovio and how will your creative testing change moving forward without the level of granularity in data we receive?

A: For the time being, our North Star is ROAS while keeping a close eye on IPMs. In the future on iOS we’ll have to rely further on upper funnel metrics, and our testing will have to be done on Android – on proxy devices – and extrapolated to iOS.

-Kieran O’Leary


Q: During your tests, did you see any difference depending on apps’ user size? I wonder if a new app having relatively small user size could have meaningful data from conversion value.

A: In our case we are using different conversion value schemas for games in, for example, soft launch where the audience is smaller. It is a question of evaluating what schema works for a specific game.

-David Mason


Q: How has the switch over to SKAN changed the way UA is run?

One of the main changes we expect are with the campaign types offered by networks but we’re seeing a shift to using contextual data and develops on this side as well.

-David Mason


Q: Are there any special impacts for apps in the kid section category?

A: This is not a category where Rovio is that active. However, I understand SKAN is good news for this category …

(I’ll chime in here: given that previously you had almost no information on campaigns for kids category apps, SKAdNetwork is actually a pretty significant increase in the amount of attribution and efficacy data for mobile marketers.)


Q: Do you feel that Facebook is still going to support your creative testing needs? If not, what will be your likely solution moving forward?

A: Yes they will, but we’ll switch our focus to Android.

-Kieran O’Leary


Q: Is it possible also to change the design of the ATT prompt? For A/B testing what works better? Would you rather test time when a prompt is shown or design of the prompt at the first open event?

A: You can not A/B test the system prompt and the text you have to provide in the plist the description “NSUserTrackingUsageDescription.” You can however A/B test when you ask, e.g. at start-up or at first ad, and also test having your own warm-up screen before popping the system prompt.

-David Mason


Next steps: webinar, or chat with us

If you didn’t already sign up for the webinar, jump on the opportunity now. Rovio talks through the design of their solution and shares a schematic which will be very interesting to other growth teams.

And, if you have additional questions, or you’re ready to start implementing, reserve a time to chat with an expert at Singular about how you can keep optimizing your growth on iOS 14.5.

Adtech upheaval: why Digital Turbine bought Fyber, and what’s happening in the ecosystem

What is happening in the mobile adtech ecosystem?

Is it the rise of platforms? The need for size to fight the heavyweight contenders of mobile advertising? Consolidation to accumulate and stockpile more first-party data in an era of increasingly scarce second and third party information? Or just a need to acquire revenue on the path to going public?

Whatever it is, we are seeing a massive acceleration in mergers and acquisitions in the mobile marketing and adtech ecosystems. Applovin bought Adjust, Vungle bought GameRefinery, Verve bought Nexstar. District M and Sharethrough. Magnite (formerly Rubicon) bought SpotX just a few months ago … and, of course, the ink has barely dried on the $400 million Digital Turbine acquisition of AdColony.

Now Digital Turbine has bought Fyber

Both are super successful adtech companies that have featured well on Singular’s ROI Indexes over the years. Both are respected. And now, both are together.

But why?

Part of the success of adtech over the last decade has been the unbundling of all the pieces and components. (Which is also one reason why the industry is so crazily complex, of course.) Now we’re seeing consolidation.

To get the inside scoop, I spent some time with Offer Yehudai, president at Fyber, and Matt Tubergen, EVP corporate development and strategy at Digital Turbine.

Essentially, it’s about offering a full meal deal.

“We’re on about 600 million devices already today, and we enable about 60 million devices a quarter … that’s more than iPhones sold globally,” Tubergen says. “The acquisition of Fyber really represents us moving into the monetization space and having a fully verticalized and fully integrated advertising stack.”

There’s obviously a lot of change happening right now in the ecosystem. Privacy, IDFA, and iOS 14 is one part of that. Another part is the alphabet soup of components and partners and players that publishers have to navigate when monetizing, and marketers when acquiring. Another part is the unprecedented scale and power of industry behemoths who suck up a lot of the oxygen in the ecosystem.

So simplification and vertical integration makes some sense.

Aggregating players for first-party data consolidation makes some sense.

And building scale to compete globally also makes some kind of sense.

Two tracks of mergers and acquisitions in adtech

“I think we see pretty much two tracks of M&A and consolidation currently in the market, and they’re all trying to achieve scale and reach,” says Fyber President Offer Yehudai. “One track is around content … can publishers or content owners create their own platform and pretty much control their own destiny … the second track we see is about building some kind of an independent tech platform for all the others who don’t want to build their own platform.”

The first is the tried and true Disney model: create content and feed that content to an owned audience. The second is a full stack tech solution that provides what Yehudai calls “the unfair advantage,” the edge that makes an adtech conglomerate smarter than the competition.

“I think it’s safe to say … app developers, advertisers, everybody in the ad space is looking for supply chain optimization,” Tubergen says.

Digital Turbine, of course, is already a sort of platform in the sense we highlighted in the recent Singular ROI Index, having the ability like a big social or search giant to manage both the supply and demand on its own terms. For Digital Turbine, that’s 600 million Android devices that it ships with from the OEM, giving it “home screen advantage” in content and app suggestion capabilities natively from the device.

As we said back in January:

OEM or on-device platforms such as Digital Turbine, ironSource Aura, and AppNext are performing extremely well. They perform on-device app discovery via a persistent experience on new devices and a set-up wizard upon activation. They can tie into the home and/or lock screens, and offer live updates on new apps to try.

Digital Turbine and ironSource Aura together account for eight spots in the 2021 ROI top charts, and offer extremely impressive ROI.

(Fyber did well also, grabbing four slots in our top ad networks ranking by itself.)

The downside, obviously, is that on-device OEM models don’t work on iOS. Apple is not about to allow app recommendation engines or not-quite-but-sort-of-like app stores on an iPhone or iPad. The upside is that the Android universe is truly gigantic.

“It’s often overlooked that carriers and OEMs actually have a huge position and leverage in the whole mobile app space,” Tubergen says. “And we believe that marrying the application providers, brands, content with OEMs and carriers, and having the technology layer that can basically be the clearing house between those companies … we’ve got a pretty compelling position.”

Add AdColony and its access to brands and expertise in video, Fyber’s capabilities, and what Digital Turbine already owns, and it’s a significant force in mobile.

For advertisers and publishers

For mobile app businesses, there are a few takeaways here.

On the one hand, there’s a new means of both acquiring users and monetizing them all within the same stack.

Vertically-integrated mobile growth stacks like this will inevitably acquire more and more first-party data which should make them increasingly effective over time at identifying and delivering high-value users. That makes them competitors for the major platforms — the Facebooks and Googles of the world, plus others — which generally means good things. More competition for mobile growth marketers’ business should ensure that there’s some downward pressure on ad pricing.

In addition, it can simplify your tech stack over time: always a good thing when application size, number of SDKs with someone else’s code, and complexity of your backend systems all matter.

On the other hand, consolidation of independent players in the adtech space can reduce diversity and decrease competition at the not-Facebook-not-Google level. And a partner becoming mission critical at both the acquisition and monetization levels ties you in tighter and tighter to a specific conglomerate.

So there are a few risks here too.

More mobile adtech M&A to come

That said, there’s almost certain more M&A activity to come.

This deal is yet another signal to other players in the industry that with all the recent mergers, acquisitions, and consolidation in the space — and technological changes driven by iOS 14 — they might want to team up with complementary companies as well and ensure they’re not left behind.

Which probably means we haven’t seen the last of the purchasing activity in mobile marketing and adtech. Not by a long shot.

The goal?

Scale, as Yehudai says. And reach. Whether that’s in terms of content or technology.

So: independent measurement matters more than ever

All of that means that independent mobile marketing measurement is more important than ever. Just one reason: while there’s clearly consolidation in the advertising and monetization spaces in mobile adtech, there’s also consolidation across the ad network and measurement categories.

Mobile measurement partners like Singular are not immune to all these massive changes in the ecosystem.

Ultimately, however, Singular remains incredibly focused on independent marketing measurement.

There are new challenges to adapt Singular data integrations with rising consolidated platforms like Digital Turbine and ensure that they work seamlessly for advertisers and publishers. And there are also new challenges as consolidation impacts the measurement space as well. Singular is tackling these challenges to ensure that marketers will be able to use the best martech stack possible with world-class cost aggregation, mobile attribution, iOS 14 and SKAdNetwork measurement, and — of course — ad monetization.

No matter which players exist in the space and how they’re configured, advertisers and mobile user acquisition specialists still need to make investment decisions. They still need smart, predictive, accurate, and unbiased information to base those decisions on.

8 reasons why digital marketers need need need granularity (from experts at Kabam, Yelp, Nexon, Postmates, & N3twork)

Pebbles on a rocky beach are granular. The white sugar that we all hate to love is granular. The stars of the Milky Way that smudge together into a glorious sheet of light are, under closer inspection by a powerful telescope, also granular.

And so is the very best of digital and mobile marketing.

Why?

“Granularity sustains profitable scale,” says Singular’s Vice President of Customer Strategy Victor Savath. “Without granularity, you can scale… but it’s hard to monitor quality.”

Granularity is important both cross-channel and within channels, Savath said recently at UNIFY conference, where he interviewed experts from Yelp, Kabam, Postmates, Nexon, and N3twork on the topic. It’s important for creative. Granularity is also important for bids and CPIs. It’s critical to evaluating publishers and sub-publishers. And it’s something that impacts your daily budgets.

But exactly what is granularity?

And what does it achieve for digital marketers?

And … how has the concept of granularity changed with iOS 14.5 and SKAdNetwork?

Granularity in digital marketing can be defined as the ability to dissect big blocky chunks of marketing activity and ad buys to see the smaller building blocks. For example:

  • If your ad campaign is spread over 15 different agencies, you can view each one individually
  • If each agency uses multiple ad networks, you can see how each is performing
  • If each ad network employs different publishers and sub-publishers in your campaign, you can dive into sub-publisher metrics
  • If you’re using varying creatives and forms of targeting, you can see how each performs
  • As users or customers engage, you can see their journey and react personally to their preferences and needs

As you can see in the video from UNIFY, experts from top mobile companies had a lot to say about the concept of granularity. Here are eight things they highlighted:


1. Granularity tells you how to maximize channels

Clearly, seeing which ad network or publisher is providing the best results is a good thing. But it’s sometimes even more important to really understand what’s working within a network or publisher.

“Obviously Facebook is the biggest social channel, but Pinterest, which is often overlooked, is an interesting play,” says Yelp’s Head of Performance, Eyal Grundstein.

The key to unlocking performance for Yelp on Pinterest was experimentation… and granularity.

Initial generic campaigns produced generic results, but when Yelp started targeting “odd things” like nail salons, click-through rates jumped 5X. Another finding: tattoos are huge on Pinterest, because people search for tattoos that they’ll consider. Targeting on tattoos and showing tattoos in the ads boosting conversions 10X.

“You can be granular not only in the targeting but also in the copy,” Grundstein says.


2. Granularity tells you which publishers are performing

Most ad networks fulfill impressions and conversions for their clients by purchasing inventory from publishers or sub-publishers. When this happens, sometimes advertisers lose the ability to optimize for maximum performance because they either lack the capability or are not looking below the top line campaign numbers to the sub-publisher results.

Hint: some will be rock stars; some will be duds.

“We have a two to three times per week process of pruning out the low performers,” says Eric Seufert, Platform at N3twork. “We kill them at the line-item level if they’re not performing.”

That process does vary from week to week, Seufert says, as publishers change. There’s some natural variance between good, acceptable, and bad, so some level of discretion is warranted. Still, the overall learning remains: advertisers need to be able to probe down to sub-publisher levels to really fine-tune performance.


3. Granularity helps you avoid ad fraud

Granularity is table stakes for avoiding fraud, says Grundstein. Impression-level data, for instance, is an absolute must.

It’s also a way to tie the technicalities of adtech to the ground-truth realities of customers, users, and your product. And there’s no better way, says Warren Woodward, Nexon’s Executive Director of User Acquisition, to really see what’s going on.

“Show me this ad in the wild,” Woodward will often ask his ad partners. “It’s amazing how many sources break down when you ask them… where is your traffic? Can you show it to me?”

And, just as source-level data allows you to pinpoint top performers, it also allows you to isolate potential fraud. Especially when you explicitly state your goalposts in the ad insertion order:

“This game that usually has a 90% tutorial completion… if we see a source as over ‘x’ number of installs and [it] deviates from that norm by over 50%… we’re going to consider that incentivized or some other type of fraud,” says Woodward.


4. Granularity helps you avoid bidding against yourself for adspace

Granularity on the publisher level helps us to “strategize and understand where not to overbid or bid against yourself,” says Yelp’s Head of Performance, Eyal Grundstein. “For example, if you’re buying on two different DSPs and they’re both buying on Mopub… they will bid up against each other potentially, especially on a particular placement if there is enough volume or if it is relevant enough.”

In other words, the ad space is complex and busy. And if you’re a significant advertiser, you’re probably using anywhere from ten to over a hundred advertising partners, which means you could potentially have campaign collisions.

There’s only one thing less cool than ad fraud, and that’s bidding against yourself.


5. Granularity helps you customize to different geographies

Country and regional level data is critical when marketing, says Kabam’s Director of User Acquisition, Andy Park.

“How people consume media across geos is different,” Park says, noting that people in China like to like and comment on ads, particularly on Tiktok, the country’s top video platform. “[One] ad got 37,000 likes and 600 comments in two days.”

Creatives come in many different sizes, shapes, and user experiences, Park says. The key is being able to present different creatives to different audiences, and react appropriately depending on which ones work.

This also enables regional targeting, says Postmates’ Director of User Acquisition Patrick Witham.

“We operate city-level targeting,” Witham says, while noting that there are some limitations with ad network data for geotargeting.

Separating campaigns for different geographies can also make overall campaign analytics more challenging, he added, and does put some limits on scale. However, tighter targeting almost always leads to better results, and “specificity drives conversions.”


6. Granularity allows you to “try wild things” and still be successful

Some of the best things you’ll do in marketing are crazy.

At least, at first glance.

“Our approach has been to build tools that allow us to be radically experimental,” says N3twork’s Seufert. “We’re building about 50 videos a week… we deploy them to test and then deploy more universally.”

Some of those videos are going to be incredible. Some are going to be horrible. But by building the engine to enable creativity at scale and fast failure, N3twork is opening itself up to those rare oddball explosions of lightning in a bottle that drive mass conversions.

Nexon’s Woodward agrees.

“Try wild things,” he says. “You want something that’s going to stand out… when you have a completely different experience, it’ll be the biggest winner or a complete loser.”

One example for Nexon was an ad that featured almost no gameplay — an extreme rarity in the mobile game ad world. Instead, it simply showed fans talking about the game. Essentially, it broke every rule… and it was the company’s biggest winner.

“It carried about a quarter of our user acquisition,” says Woodward.


7. Granularity helps you avoid poorly performing genres of publishers

Sometimes you want to avoid one publisher in particular. Sometimes, though, you want to avoid an entire genre of publishers.

That’s exactly the scenario that Kabam’s Park found himself in (watch the video for full details… including precisely what he was trying to avoid.

Some things just don’t work for your company, your brand, your product, or your app. And granularity enables you to avoid them.


8. Granularity helps you test creative versus creative

Every marketer wants to know which ad units are performing. That’s table stakes… and yet also an example of granularity.

Smart marketers also want to know their conversions from different creative types: banner, text, interstitial, video… and playable ad. You just might be surprised at what you find.

For example, playable ads doubled Nexon’s app installs from one particular source, says Executive Director of User Acquisition Warren Woodward.

“Now we’re making as many playables as possible,” Woodward says. “If you’re not games, think about other ways you can make interactive ad units. The rest of us are… you won’t be in the game if you’re not.”


But what about iOS 14.5 and SKAdNetwork?

Old-school mobile marketing relied on granular device-level data to get detailed data on impressions, clicks, installs, and post-install activity, and on iOS that is no longer all relevant. (For now Android is business as usual.) On devices running iOS 14.5 and later (which is now almost all devices) you can only get that level of data if people opt in to tracking … which you can only know after they install your app.

For that reason — and the fact that 75-85% of people are not allowing tracking via the App Tracking Transparency pop-up — your best source of data arrives via Apple’s SKAdNetwork data.

The good news for mobile marketers: it’s deterministic.

The bad news: it’s incomplete by design, it arrives at variable times, it’s adopted with different practices and policies across different ad networks, and it’s explicitly not device level in order to be privacy-safe.

This doesn’t mean marketing optimization on iOS is over. It does mean that mobile growth marketers need to use new ways of measuring advertising and marketing success and learn to be comfortable with a certain missing layer of granularity. However, using Singular SKAN, marketers can still get good, usable, reliable data on which to base marketing optimization tactics.


Summing up

Granularity isn’t just a nice-to-have. It’s an incredibly useful attribute for marketers who want to scale profitably.

The good thing: it’s easy to get on Android.

The challenge: you have to work for it — and earn it — on iOS, and in some cases, you simply can’t get it.

Dig deeper: See how the best growth marketers succeed.

IDFA survey: 62% of consumers will not allow app tracking in iOS 14

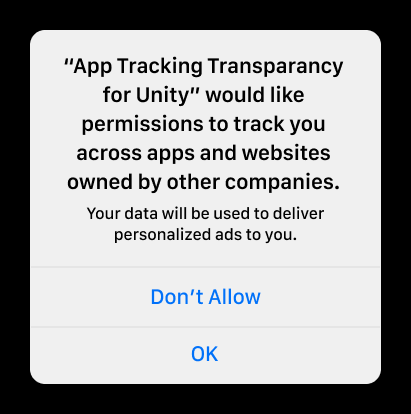
Ad personalization capability will drop by 44% in early March when Apple releases iOS 14.5. That’s when Apple’s new privacy provisions will be fully implemented and each new app install or update will be required to ask permission for tracking.

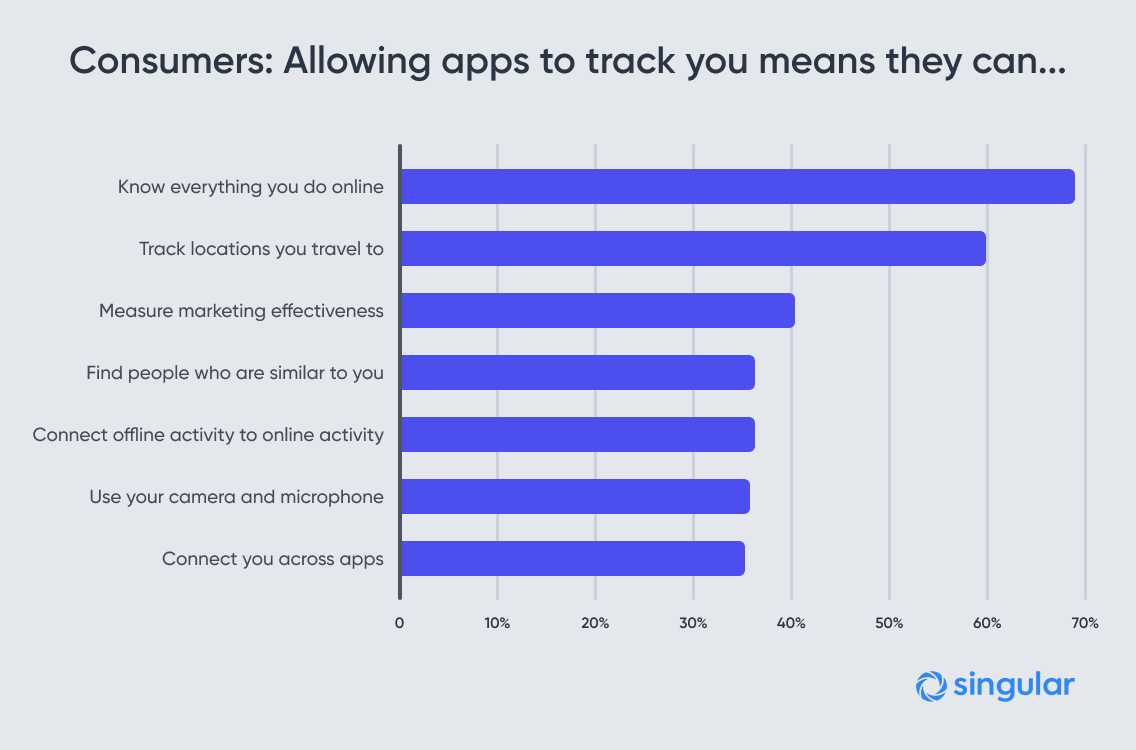
In a survey of 600 consumers conducted this February, 61.5% of people said they would click Don’t Allow if their phones popped up Apple’s new App Tracking Transparency prompt.

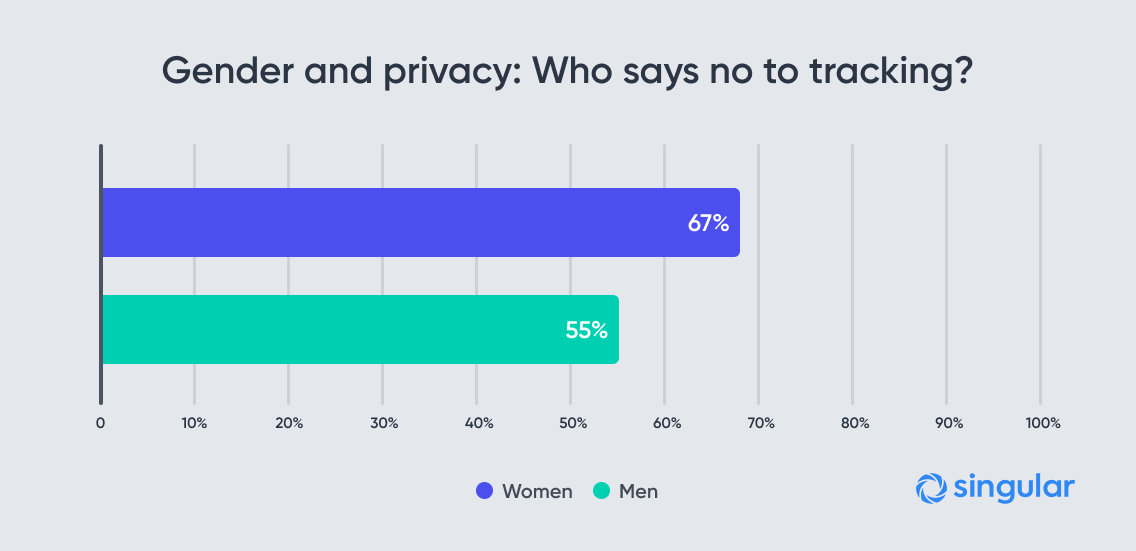
Interestingly, there are some significant gender differences.

And there are also certain factors that consumers say will influence them to click OK.

Almost exactly a year ago, I analyzed data from 390 million devices to identify how many people were implementing Limit Ad Tracking — Apple’s older version of privacy protection from tracking on iPhone and iPad. What we found was that Limit Ad Tracking on iOS was up to 31.5%. If our 2021 survey results hold true in real-world customer behavior, almost twice as many iOS users will essentially be invisible on a granular per-device basis to mobile marketers.

Consumers: who will say yes to tracking in iOS 14?

Interestingly, women and men show significant differences in desire for privacy, or at least not allowing tracking. While in both cases a majority will not allow tracking, 67% of women say no while only 55% of men dissent.

There are also key differences by age.

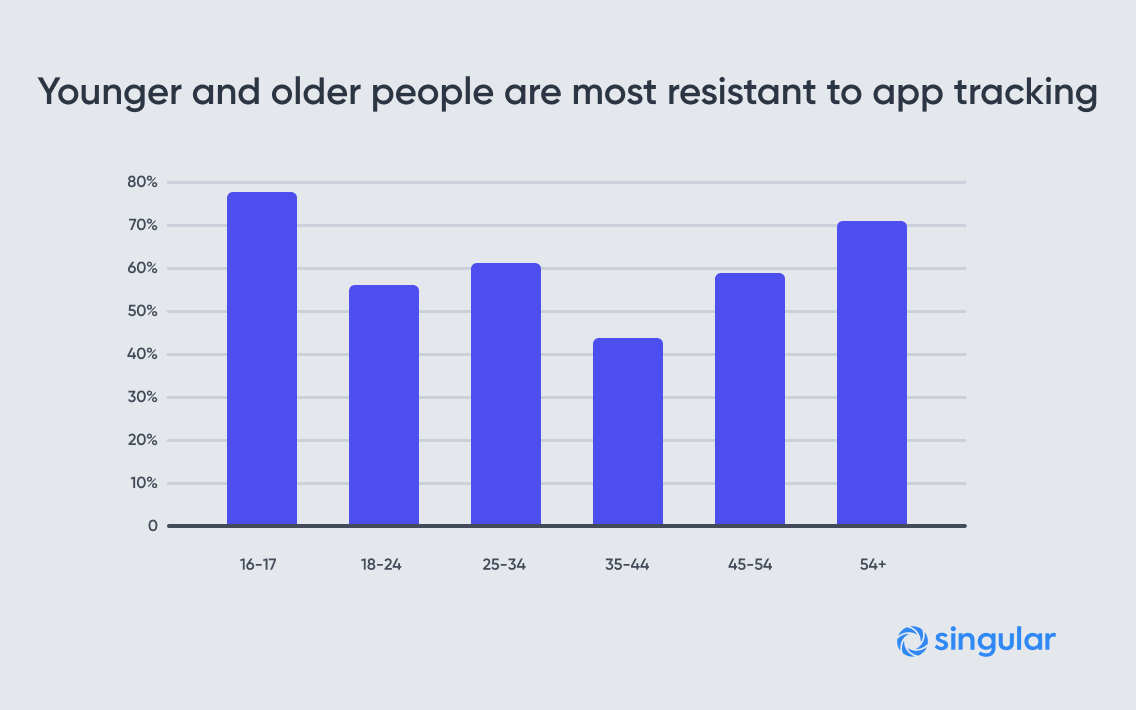
Younger and older people tend to say no to tracking more than middle-aged people, and the youngest are the most opposed. Almost four in five teenagers aged 16 or 17 say they’ll click Don’t Allow in the ATT prompt, while 71% of those aged 54+ agree.

35-44 year-olds were the most accepting of mobile tracking, with only 44% saying they won’t allow tracking. And that’s the only age category where a majority of people are OK with being tracked.

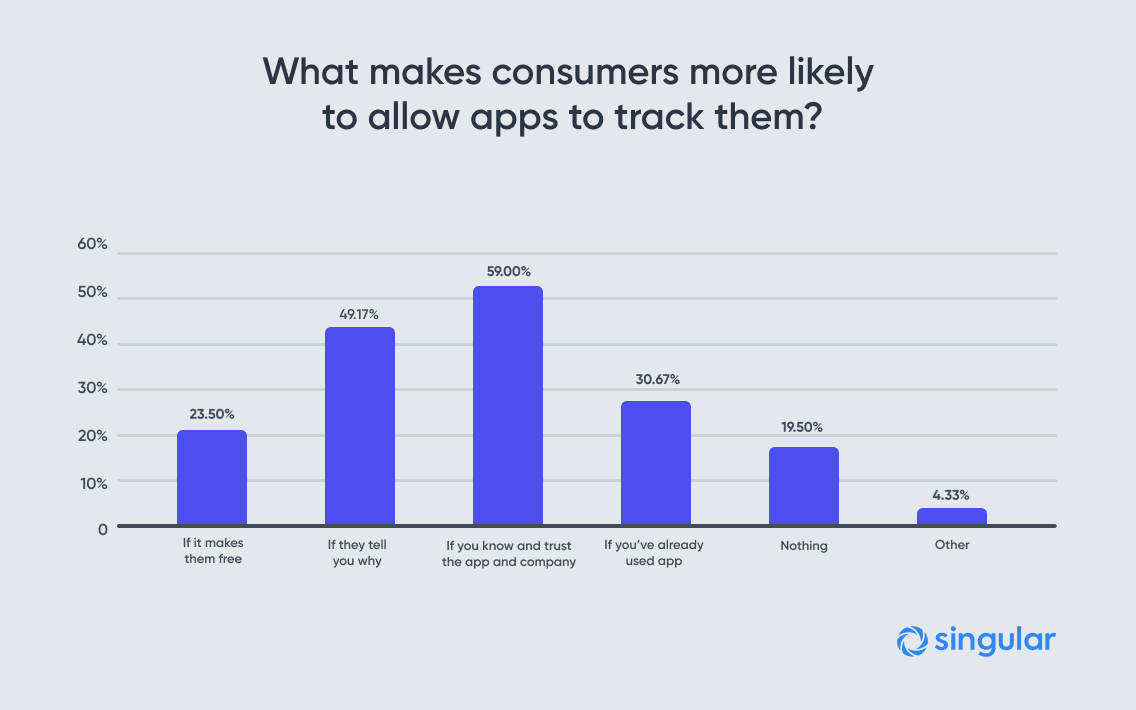
There are, however, some reasons that will make it more likely for consumers to say yes to tracking. Unfortunately, they’re not necessarily good ones for startups or lesser-known companies, because the single biggest predictor of consumers providing consent for tracking in iOS 14 is brand. How well people know you — and if they trust you — is the single most important factor making them more willing to allow tracking.

There is one other big factor in favor of tracking, but it has nothing to do with what you might expect: ensuring apps stay free.

Rather, it’s simply explaining what you’re going to do with the data you collect.

59% of people will allow apps from brands they know and trust to track them. Almost 50% will be more willing to allow tracking if apps can explain why they want users’ data. This makes perfect sense, but it won’t solve too many problems for marketers who have only two short lines of small text in the ATT pop-up to explain what they’re doing. On the other hand, if you can explain in-app what data you want and why you want it, this survey suggests you have a good chance at getting tracking consent.

Note, however, that for 20%, no reason will suffice.

Nothing will convince them to allow app marketers and publishers to track them.

How important is privacy? Extremely important

That makes sense because 70% of people say that digital privacy is “extremely” important to them, and a massive 93% say that digital privacy is either extremely or somewhat important.

There’s no gender difference in the importance of privacy, but there is an age difference.

According to our survey results, privacy becomes more important as you get older. 75% of those 35 or older say digital privacy is “extremely” important versus 65% of those 43 or younger. (If you’re wondering about the relationship between this data and the U-curve graph on tracking by age above, 69% of those aged 16-17 were also on the “extremely” important side, meaning that young and middle-aged adults were least concerned about digital privacy.)

Privacy vs money: which wins

Interestingly, when given the choice between privacy or paying, most people chose paying.

At least, on a survey.

73% of consumers say they’d rather have more privacy even if it meant having to pay for more apps or services than they currently do. Only 27% said they would sacrifice privacy for more free apps and free services.

Reality will have the final word here, however.

It is true that consumers have chosen paid services, often with subscriptions, increasingly over the last few years. We’ve seen that in Netflix and Disney+ as well as paid news subscriptions, gaming subscriptions, and even emerging methods of buying and accessing mobility services like cars. An open question, however, is whether this will translate into continued growth in mobile subscriptions in the global app economy.

And in fact 40% say they would not pay $1 per year for even massive and engaging apps like Facebook or Google.

Mobile publishers might take solace in the fact that 60% say they would pay something, but here’s an important point. Even if 100% of American users paid $100/year for an ad-free Facebook, Facebook would lose money on the deal.

Facebook earns an average of $41/user every quarter for users in the U.S. and Canada, so even at the highest price we surveyed, Facebook revenue would drop drastically as a paid service. The reality is that most consumers — and maybe most mobile marketers too — really don’t have any clue how lucrative Facebook is per user, especially in North America.

People do not really understand digital privacy

The reality of digital privacy, however, is that most people don’t really understand what apps and websites and track.

75% of respondents believe that allowing apps to track you means that they “know everything you do online,” which is far from the truth for even the biggest platforms on the planet, and not even in the ballpark for most mid sized to small mobile publishers. And 64% think that allowing apps to track you means that they can track their locations — an unfortunate misunderstanding given that the meaning of the word “tracking” often can refer to physical location. In reality, of course, only apps with location privileges — which they have to ask permission for separately — can directly know where you are.

Consumers are savvy to the fact that marketers can connect offline activity to online activity, however.

But only 30% know that the digital tracking that Apple is working hard to get user permission for is actually related, more than anything else, to measuring marketing effectiveness. That’s something that might not come as a shock to most digital marketers, but it will also cause a grimace: consumers are largely unaware of the actual stated purpose of Apple’s IDFA, or Identifier for Advertisers, which iOS 14 and App Tracking Transparency are, by and large, aimed at.

Perhaps also surprisingly, only 55% of consumers think that Apple’s new privacy provisions in iOS 14 will actually increase their digital privacy.

55% say yes, but a full third are not sure. And over 10% say no, it won’t … perhaps being cynical and either thinking that tech companies will find ways around the privacy guidelines, or that the guidelines themselves are more window dressing than reality.

Astonishingly, iOS and Android users are almost identical in their responses. While 53% of Android users say Apple’s policies will increase privacy, only a few percent more — 56% — of iOS users agree. And 35% of them are not sure.

Most trusted tech companies: Google and Apple

Google is consumers’ most-trusted big tech player, with 43% of respondents picking the Mountain View company. Apple came in at 37.5%, but 36% said that they didn’t trust any of the big tech companies.

35% trust Amazon with their private data, and 23% trust Facebook.

Not shockingly, if you split this by iOS versus Android users, iOS users think Apple is the most trustworthy big tech company, with 45% picking the Cupertino iPhone maker. But 39% of them trust no tech companies at all. For Android users, 44% trust no tech companies, with 40% trusting Google.

Summing up: IDFA scarcity and a sea change in marketing measurement

It’s possible that the death of the IDFA has been prematurely predicted. If 40% of iOS users do actually allow marketers to track advertising effectiveness by clicking OK in the ATT pop-up, that’s not insignificant.

(In fact, you could argue that 40% is a big enough percentage to make aggregate judgments about the other 60%, at least in some things.)

But even at a 60% reject rate, it’s clear that Apple’s privacy-safe SKAdNetwork attribution framework is the way to go for the majority of marketing measurement in the mobile app space on iOS. That’s especially true when you take into account the massive growth we saw last year in the Limit Ad Tracking “on” segment on iOS … it had doubled since 2016.

If that continues — and the global trend is towards more privacy, not less —- SKAdNetwork is likely to be the default attribution methodology for 80% or more iOS app installs within a year or two.

We ran this survey at Pollfish to 600 Americans over the age of 17 in February 2021. The panel is evenly spread across six age categories and is 50.7% men, 49.3% women. Of those who reported mobile platform, 59% are on iOS and 41% are on Android.

Mixtiles co-founder on marketing, identity, privacy, iOS 14, IDFA, and app vs web

Sometimes a smaller top of the funnel is better than a big gaping maw that hoovers any and all potential customers in. And sometimes the web is a better option than a mobile app.

Those are just two of the learnings from half an hour with Mixtiles co-founder Eytan Levit on today’s hot topics in the iOS 14 era: is web better than app? Can we live without the IDFA? How do you measure marketing effectiveness with less signal? Is SKAdNetwork the only answer now on iOS?

If you’re a marketer who is wondering how to navigate the new privacy-safe reality in Apple environments, Mixtiles is a good company to look to for insight:

  • Super-fast growth over the past few years
  • Hot D2C (direct to consumer) category
  • Heavily focused on iOS
  • Overwhelmingly multi-channel and multi-platform user journeys
  • Not dependent on IDFA

Watch the whole video below, and subscribe to the Growth Masterminds podcast while you’re at it:

Email, first-party identity, and booting people from the funnel

It won’t come as a shock to marketers that first-party data will matter more than ever in the emerging privacy-safe world of marketing and attribution. And email addresses, even though they’re decades-old technology, are great first-party data for identifiers.

They actually help in multiple ways:

  1. Simple, first-party cross-platform attribution to measure marketing effectiveness
  2. Follow-up mechanisms to potential customers who don’t complete their purchase
  3. Friction point to weed out people who won’t buy

“We start collecting emails very early in the funnel, just as a response to how can we monitor that journey,” Levit says. “Actually collecting emails early really helps … we found out that losing the people that don’t move forward in the funnel because they don’t want to leave their email … it’s not a huge loss because most of them usually also don’t end up buying.”

Levit is probably the fifth top-level marketer to have told me in the last month or so that adding friction to the customer journey can be a great thing, something we never would have heard or even dreamed of years ago. And this method, which aligns with what Singular clients like Draft Kings, Riot, Digit, and Truebill are doing, not only helps marketers focus on those potential customers who are most likely to convert. It also gives them a gauge for assessing cross-platform marketing effectiveness.

Does an ad on Instagram, for example, result in a sale? Even if not right away, perhaps two or three months later?

As a Mixtiles customer, I’m pretty sure that’s how it worked for me. But without an email address — or another step Mixtiles takes that I’ll talk about below — marketers don’t know. And that means they could end up shutting down top-performing channels accidentally.

Getting attribution right matters. It really, really matters

Cross-channel measurement was a big deal for Mixtiles in 2020, but it wasn’t a smooth journey. In fact, in early attribution models, something odd, counterintuitive, and downright dangerous appeared in the data.

“We basically found out that every time we improved the email marketing machine, Facebook spend goes up and profitability tanks,” Levit told me.

This is of course insane: owned data and owned platforms getting more successful at delivering customers should not increase paid spend — what Levit calls “toll platforms” — and should increase ROI because you’re not buying every customer any more … you are earning them organically via owned platforms.

More tweaking, uplift models, UTM parameters, and a bit more sophistication separated out what email did, what Facebook did, what Google did, and revealed that over-eager attribution claims were eating profit.

“All these platforms … they steal attribution from other channels all the time,” Levit says.

One surprisingly low-tech way to run a sanity check on attribution models?

An after-purchase survey.

“We learned that putting a pre-purchase and post-purchase survey actually works,” Levit says. “It’s not 99% accurate, but it’s like 80% accurate. So if you want to look at things from the big picture and to understand — big picture — what works and what doesn’t, especially for channels that are harder to attribute like YouTube or television, that’s actually a really useful tool.”

Count me shocked when I heard that, because if there’s anything I hate as a consumer it’s the website survey pop-up or the how-did-we-do-today questionnaire in a store or restaurant, or the post-purchase survey in a digital retail context.

But Levit’s no idiot.

He’s not presenting a 10-question survey to his valued prospects and clients — something that I’d argue is sure to annoy and anger them. Instead, it’s simply one single question. Something like, I imagine: “Where did you first hear about us?”

That doesn’t even present as a survey. And it can be answered by a single click or tap on a laptop or mobile device, which means it’s incredibly easy. The result is a quick straight-from-the-horse’s-mouth sanity check on your technology. Mixtiles runs it on about 5% of their customers, and it sounds like an incredibly valuable way to ensure your marketing is on track.

While Levit won’t reveal which channel, he says this survey method was critical in determining that an apparent money-losing marketing channel was actually ROI-positive and has great long term impact. (Don’t tell him, but I’m guessing the channel he’s talking about is good old-fashioned TV ads.)

iOS 14 as an opportunity

Interestingly, Mixtiles is viewing iOS 14, App Tracking Transparency, and the impending downfall of the IDFA as a significantly-useful marketing identifier as an opportunity, not a problem.

Levit compares iOS 14 to the introduction of CCPA, the California Consumer Privacy Act last year. And he thinks that now, like then, Mixtiles can steal a march on the competition.

“We did benefit, by the way, from the rollout of the new privacy measures that happened in California,” he told me. “We came very well-prepared and we were like, we had one month with CPAs that were super low in California and we were having a blast.”

The plan for Mixtiles in 2021 is to get a similar bump in the early days of iOS 14’s full privacy measures and ATT rollout.

While prepared for a dip in advertising effectiveness — perhaps 20-30% — Levit says Mixtiles is investing “serious resources” in preparation for losing IDFAs, and planning to be one of the brands that is ahead of the curve in technology and technique.

Mobile web: spending more

Mobile web has downsides, as mobile marketers know. It’s not as sticky as an app. And, often when you get there, you’re in a sandboxed browser opened by Instagram or another app, and your potential customers don’t have access to their saved passwords, stored credit card numbers, or the ability to save a bookmark.

The result isn’t great, but it’s also not bad.

Mixtiles expected a hit on retention rates when they ramped spending on mobile web, and that does happn. However, it’s not as bad as they feared, and Levit says they were so surprised by their web growth that they shifted a lot of their spend there. (One thing I’ve heard from other marketers recently that might be at play here as well: ad costs are much lower on the mobile web than in apps, so you can withstand lower metrics and still come out ahead on ROI and ROAS.)

Plus, Mixtiles sees larger orders on web, making that marketing shift make sense.

Add it all up: YMMV, but test

Ultimately, of course, every brand and every marketer is different. What the Mixtiles experience does highlight is that you can swim upstream, try something different, and get happily surprised at how well it works.

If you’re interested in learning more about IDFA, SKAdNetwork, iOS 14, and how Singular can help you run and manage cross-platform marketing measurement, give us a chance to show you.

10 new players, 5 emerging platforms, and 2 industry giants: Singular ROI index 2021

Where do mobile marketers get the highest return on investment for their advertising dollars? In more than a few surprising places, according to Singular’s 2021 ROI Index.

In fact, there are no fewer than 10 new ad networks in the 2021 ROI report in various regions, on both major mobile platforms, and for various verticals. That’s the most in my memory and a compelling indicator of significant change in the mobile advertising space.

Appropriate, I suppose, during COVID and in the age of iOS 14.

Perhaps even more significantly, we have five major emerging platforms that are challenging the perennial heavyweights of digital advertising, Google and Facebook.

Get the free Singular ROI Index here.

10 new players

Seven ad networks made the 2021 ROI Index in various regions and categories for the very first time. They include traditional ad networks, on-device out of the box OEM players, and influencer marketing networks.

In alphabetical order, they are:

  • Aura ironSource
  • Blind Ferret
  • BlueStacks
  • Crossinstall
  • Fluent
  • Jetfuel
  • Mistplay

In addition, three networks that have been on regional or vertical top lists before made our biggest and most important list this year: the global ROI leaders. You’ll recognize their names:

  • Digital Turbine
  • Fyber
  • LINE Ads

5 emerging platforms

Perhaps even more interesting are five major emerging platforms. These are companies whose names you know: they’re not new to the mobile advertising space. But what’s important about them is that like Facebook and Google, they drive their own supply and they allow advertisers to satisfy demand right within on-platform tools.

That’s powerful in an era of increased competition and decreased data sharing. This year we’re seeing that power manifest itself: these five platforms take no fewer than 86 positions on the various regional and vertical-focused top lists.

They include:

  • Apple Search Ads
  • BlueStacks
  • Snap
  • TikTok
  • Twitter

Apple’s probably not a surprise, but where last year Search Ads was on everyone’s list somewhere, this year the company ranks first or second on every category in which it competes. Bluestacks is more than 400 million passionate Android gamers with crazy good retention. Snap and Twitter rank on no fewer than 25 out of 27 possible top lists, pushing them right up under Google and Facebook. And TikTok is simply a growth beast.

There’s. So. Much. More.

There’s so much more to say, so … get the report already. We also saw impressive results from traditional mobile ad networks like ironSource, Liftoff, Tapjoy, Moloco, Aaki, Chartboost, and more.

Plus, Unity had a massive showing, ranking on no fewer than 22 out of 27 possible top lists. (Frankly, I’ve undersold Unity in this blog post.)

For all the insights, including on influencer marketing, social (and not just Facebook!), search (and emerging issues there), and no fewer than eight hidden gems and honorable mentions, download the full report. The hidden gems are especially interesting: good returns, in all cases, but not always the volume that we see with other players.

In other words: opportunity.

The full report is available, for free, here.